

Photovoltaic Lease Prices 2026: €3,000–5,000 per Hectare
Photovoltaic lease prices in Germany in 2026 typically range between €3,000 and €5,000 per hectare per year, many times the classic arable-land lease. At sunny locations with a short grid connection, investors pay up to €5,500 per hectare at the top end. How high the lease for your specific site turns out depends above all on the electricity yield, and that is determined by solar radiation, the grid connection point and EEG eligibility.
"Check in 10 seconds — no email, no callback"
Key Points at a Glance
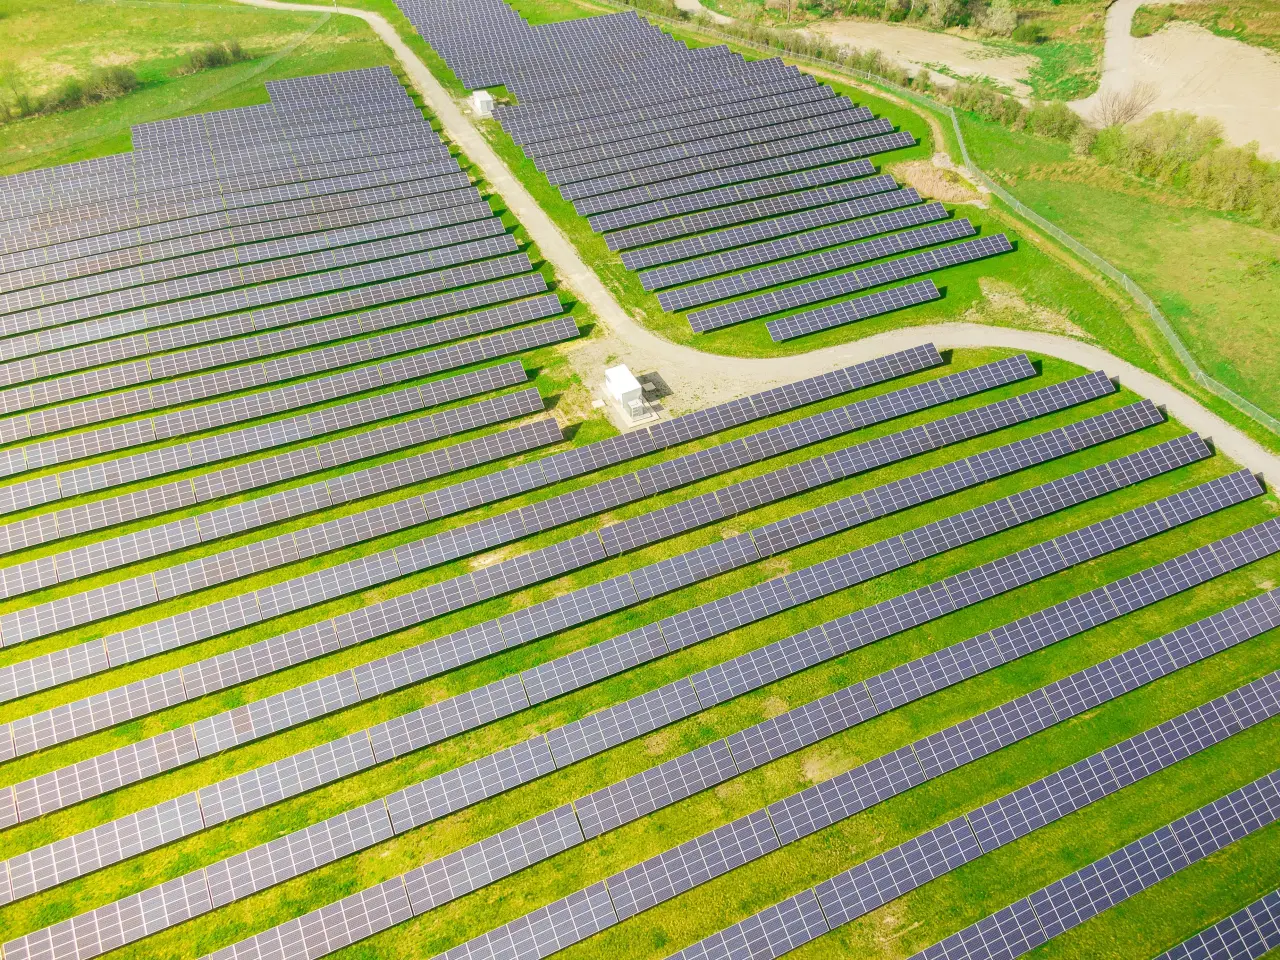
Ground-mounted photovoltaics earn €3,000–5,000 lease per hectare per year in 2026, up to €5,500 at prime locations.
More important than the region is site quality, grid proximity, radiation and plot shape decide the price.
The main price drivers are solar radiation, distance to the grid connection point, EEG eligibility, land size, contract term and competition among developers.
Compared with the average arable-land lease of €407/ha (existing contracts, Destatis), a solar park earns you roughly 7 to 12 times as much.
The lease comes out of electricity revenue: at 4.79 ct/kWh (July 2026 auction) one hectare of solar park earns roughly €48,000 a year, and the lease is about 6–10% of that.
Worked example: 20 hectares at €4,000 bring €80,000 a year and €2.4 million over 30 years, around €3.2 million with 2% indexation.
Land near a substation? A partial area for a battery storage system earns €20,000–30,000/ha.
Photovoltaic Lease per Hectare: an Overview of 2026 Prices
The decisive factor for the lease is the electricity yield of the site: the more electricity a system can generate over the year, the more lease the operator can pay. That is why lease prices for ground-mounted PV in 2026 move within a clear corridor.
| Category | Typical lease (€/ha/year) | Comment |
|---|---|---|
| Lower bound of viable projects | €3,000 | weaker radiation, longer grid connection |
| Common market average | €3,500–4,500 | solid site with good grid access |
| Prime locations | €5,000–5,500 | high radiation, nearby grid connection, several bidders |
Prices well above €5,500 per hectare are rare and usually tied to special conditions (e.g. a very short grid connection, high buildable area, or revenue sharing instead of a fixed lease). Offers of €10,000 or more per hectare are almost always bait offers, scrutinise them carefully.
Solar Park Lease Prices by Site Quality
More important than the federal state is the quality of the site: solar radiation, distance to the nearest grid connection point and the shape of the plot determine where your offer lands within the range. As a regional rule of thumb: in the south higher radiation lifts the price, in the east and north free grid capacity is often decisive. The following table summarises the typical ranges for 2026.
| Site | Typical lease (€/ha/year) | Characteristics |
|---|---|---|
| Standard site | €3,000–4,000 | solid irradiation, feasible grid connection, typical plot shape |
| Good site | €4,000–5,000 | high irradiation or short grid connection, well-shaped plot |
| Premium site | up to €5,500 | substation in reach, large contiguous area, several bidders |
| Agri-PV (dual use) | €1,000–3,000 | land remains in agricultural use, lower module density |
These ranges are guide values for typical ground-mounted projects. The actual lease for your land may be higher or lower, because it always depends on the specific site factors. That is exactly why an individual assessment pays off before you lease out your land for a solar park.
Where the lease comes from: electricity revenue per hectare of solar park
The range of 3,000 to 5,000 euros is not negotiating folklore; it can be derived from the power market. Solar parks above 1,000 kWp only receive EEG support through a Federal Network Agency (Bundesnetzagentur) auction, and the award values show the most an operator can earn per kilowatt-hour:
| Bid deadline | Volume tendered | Bids | Awards | Award values | Volume-weighted average |
|---|---|---|---|---|---|
| 1 March 2026 | 2,295 MW | 532 bids / 4,622 MW | 268 | 3.99–5.10 ct/kWh | 4.94 ct/kWh |
| 1 July 2026 | 2,135 MW | 401 bids / 3,170 MW | 261 | 4.38–4.97 ct/kWh | 4.79 ct/kWh |
Roughly 1 MWp of module capacity fits on one hectare, and 1 MWp generates around 1 gigawatt-hour of electricity a year in Germany. At 4.79 ct/kWh that is about €48,000 of electricity revenue per hectare per year. Out of this the operator pays for modules, racking, inverters, grid connection, operation, financing, the dismantling reserve, the municipal participation under Section 6 EEG and your lease. A lease of 3,000 to 5,000 euros therefore corresponds to roughly 6 to 10 percent of electricity revenue.
This calculation is deliberately rough; radiation, coverage density and the area actually permitted shift it in both directions. But it explains three things worth keeping in mind with every offer: the lease cannot rise without limit, because a project with an inflated lease no longer wins in the auction. Every kilometre of connection cable comes out of the same pot as your lease. And an offer of 10,000 euros per hectare would claim about a fifth of total electricity revenue, which is hard to sustain over 30 years. How auctions and statutory feed-in tariffs work in detail is explained in our guide to feed-in tariffs 2026.
The awards of the July 2026 round were spread widely across the country: Bavaria 75 awards with 429 MW, Baden-Württemberg 41 with 266 MW, Rhineland-Palatinate 25 with 239 MW, North Rhine-Westphalia 21 with 233 MW and Lower Saxony 28 with 225 MW (Federal Network Agency, 18 August 2026). Good sites are therefore not limited to the south.
Solar park lease income: a worked example for 20 hectares
What the range means for a typical farm is shown by a worked example with 20 hectares of contract area. The indexation of 2 percent per year is an assumption for illustration; the actual adjustment follows the indexation clause in your contract.
| Scenario (20 ha) | Lease per year | Total over 30 years without indexation | Total over 30 years with 2% indexation |
|---|---|---|---|
| Lower range, €3,000/ha | €60,000 | €1.80 million | around €2.43 million |
| Market middle, €4,000/ha | €80,000 | €2.40 million | around €3.25 million |
| Good site, €5,000/ha | €100,000 | €3.00 million | around €4.06 million |
| For comparison: arable lease, €511/ha (new lease) | €10,220 | €0.31 million | – |
Two points decide whether the numbers work out like this for your land. First: what does the per-hectare price refer to? Some offers pay on the entire contract area, others only on the fenced or module-covered area. Setback areas, compensation areas, access tracks and cable routes make the difference, so the reference area belongs explicitly in the contract. Second: when does the money start? The full lease usually begins only with construction or commissioning. For the planning years before that, a reservation or option fee should be agreed, otherwise the first years of the table read zero.
The income is taxable, and the land may switch to real property for tax purposes. The details are explained in our guide Leasing arable land for photovoltaics and taxes.
What Influences the Photovoltaic Lease Price?
Whether your land lands at the upper or lower end of the range is decided by six factors.
1. Solar Radiation and Slope
Radiation is the most important value driver. Bavaria and Baden-Württemberg reach up to 1,100 kWh/kWp per year, northern Germany rather 950 kWh/kWp. Ideal is terrain that slopes gently to the south; a north slope of up to 5% and an east-west slope of up to 10% are usually still acceptable. The higher the expected yield, the higher the lease.
2. Distance to the Grid Connection Point
The solar electricity has to reach the grid. The further away the nearest suitable grid connection point (substation) is, the more expensive the connection, and the less remains for the lease. As a rule of thumb, a distance of around 500 metres per hectare of plant area is still considered viable. A grid connection right on the doorstep is one of the strongest lease levers of all.
3. EEG Eligibility and Disadvantaged Areas
If a site is eligible for funding under the Renewable Energy Sources Act (EEG), this secures the operator a calculable remuneration over 20 years, which raises willingness to pay. Whether a site falls within the so-called area framework depends, among other things, on whether it lies in a disadvantaged area or in a corridor along motorways and railway lines. This corridor was widened from 200 to 500 metres by the EEG 2023 on 1 January 2023 (Section 37(1) no. 2 EEG); Solarpaket I (in force since 16 May 2024) additionally opened disadvantaged areas nationwide and raised the bid cap per installation to 50 megawatts. What this means in detail is explained in the guide Solar Package 1: what applies to your land in 2026. Conversion/brownfield sites (e.g. former military or landfill areas) are classic EEG sites too. (Note: the details of the area framework and the specific remuneration rates are continually adjusted by EEG amendments. Have the current status checked individually for your site.)
4. Land Size and Buildable Area
Larger, contiguous areas spread the project costs over more capacity and are therefore more economical. For EEG-funded ground-mounted sites, around 5 hectares is the practical lower bound, and rather 10 hectares outside the EEG. How much of that may actually be covered with modules is ultimately set by the building permit. South-facing areas reach up to 1.2 MWp per hectare, east-west systems up to 1.4 MWp.
5. Contract Term and Indexation
A long, secured term increases the value for the operator, and thus the possible lease. Common terms are 20 years base plus extension options. Important for you as the owner: an indexation clause that links the lease to inflation so the payments do not lose value over 30 years.
6. Developer Competition and the Power Market
If there are several interested parties for your land, competition drives the lease up. Conversely, low wholesale electricity prices and high interest rates push bids down. The market value of solar fluctuates strongly: the 2025 annual average was 4.508 ct/kWh, the April 2026 monthly value only 1.317 ct/kWh. Since the Solar Peak Act (Solarspitzengesetz, in force since 25 February 2025), newly commissioned plants receive no EEG support in quarter-hours with negative wholesale prices (Section 51 EEG); the lost periods are added to the end of the support period. Both are operator risks, but they feed into the bids and therefore into the lease a developer can offer. Therefore, lease preferably to financially strong, strategic investors who are actively involved in electricity trading and can pay your lease reliably over the entire term.
Solar Park Lease vs. Arable-Land Lease
The difference from classic leasing is enormous. According to the 2023 Agricultural Structure Survey of the Federal Statistical Office (Destatis), the average arable-land lease was €407 per hectare per year across existing contracts and €511 for new leases. A solar park, at €3,000–5,000, therefore earns roughly 7 to 12 times the existing-contract lease and still 6 to 10 times a new lease, with income that is long-term secured and plannable.
This is particularly interesting for low-yield or disadvantaged arable land: what yields little agriculturally can become a top earner as solar land. If you are wondering whether this is worthwhile for your site, our overview of how to Lease Land for a Solar Park and which areas qualify will help.
If you mean the agricultural lease per hectare: the current values for arable land and grassland, the influencing factors and how to determine the locally customary lease are covered in the guide Arable-land lease prices. This article deals exclusively with the lease for solar land.
Market development 2026: why developers are looking for solar land
Demand for suitable ground-mounted photovoltaic sites is high in 2026 and will stay that way for the foreseeable future. The driver is written into law: Section 4 of the Renewable Energy Sources Act (EEG) targets 215 gigawatts of installed photovoltaic capacity by 2030 and 400 gigawatts by 2040, with roughly half of the additions expected on open land. At the end of 2025, around 117 gigawatts were installed according to the Federal Network Agency (press release of 8 January 2026); reaching the target would require an average of 19.6 gigawatts per year from now on, more than in any year so far. A large share of that will be built as solar parks on land that was previously farmed.
Two figures from 2026 show how strongly this push is already working. In the first half of the year, according to the German Solar Association (BSW-Solar, evaluation of the Market Master Data Register, 14 July 2026), around 54 percent of newly installed capacity came from ground-mounted systems, about 4,000 megawatts, a third more than in the same period of the previous year. And the Federal Network Agency's tender for ground-mounted systems on 1 March 2026 was roughly twice oversubscribed, with 4,622 megawatts of bids for 2,295 megawatts on offer; the volume-weighted award value was 4.94 cents per kilowatt-hour (Federal Network Agency, 12 May 2026). Almost half of the awarded capacity was on corridors along motorways and railway lines, a third on arable and grassland in disadvantaged areas. Developers are competing precisely for the land categories that rural owners typically hold.
Large project developers are continuously looking for sites from around 5 hectares, often considerably larger. Two developments widen the field further. Since Solarpaket I (May 2024), arable and grassland in disadvantaged areas is open nationwide for EEG support; the federal states may only restrict it once ground-mounted systems occupy more than 1 percent of their agricultural land (Section 37c(2) EEG). And agrivoltaics, meaning electricity generation and farming on the same land, is increasingly successful in the auctions: in March 2026, "special solar installations" won 59 awards with 439 megawatts. The separate sub-segment provided for in the EEG, however, has not been applied so far for lack of EU state-aid approval (Section 101 EEG); agrivoltaics competes in the regular ground-mounted segment and receives a bonus of 0.5 ct/kWh.
At the same time, land take is politically capped: Section 37(4) EEG limits ground-mounted systems on agricultural land to 80 gigawatts until the end of 2030 and 177.5 gigawatts thereafter. According to the German Solar Association this corresponds to around 0.5 percent of agricultural land. Farmers' associations and many municipalities nevertheless remain sceptical, fearing competition for good soils and rising land prices. In practice this means municipalities prefer to approve solar parks on low-yield land and ask for a share; Section 6 EEG allows operators to pay host municipalities up to 0.2 cents per kilowatt-hour. For you as a lessor this tends to be an advantage: a low-yield, grid-close plot in a disadvantaged area is currently the most sought-after type of site.
For the lease this means the ranges of 3,000 to 5,000 euros per hectare are likely to remain stably high given demand. An automatic increase cannot be inferred from that, however. Award values fell from 4.94 ct/kWh in March to 4.79 ct/kWh in July 2026, the EEG 2027 shifts more market risk onto operators (see below), and grid connection is becoming a bottleneck at many substations. This weighs on willingness to pay per hectare rather than on demand for land. Owners of a suitable plot therefore negotiate from a strong position, but should prefer an indexed fixed lease to a mere hope of rising prices.
EEG 2027: what the draft means for your lease
The federal cabinet adopted the government draft of the EEG 2027 on 29 July 2026; parliamentary deliberation began in September 2026, and EU state-aid approval is still pending. Until it is promulgated, the EEG 2023 as amended by Solarpaket I and the Solar Peak Act applies. Four points of the draft matter for solar parks on agricultural land:
- More auction volume: 14 gigawatts per year for ground-mounted systems from 2027 to 2032, instead of the previously planned 9.9 gigawatts. That points to continued high demand for land.
- End of the fixed tariff for new plants in favour of direct marketing. For solar parks above 1,000 kWp little changes, as they already market directly today.
- Feed-in capped at 70 percent of capacity at the grid connection point. Less peak feed-in tends to mean less revenue per hectare, often combined with a storage system.
- Agrivoltaics and floating/peatland PV: the never-applied sub-segment is to be dropped in favour of a 0.5 ct/kWh bonus.
For you as a lessor this means: contracts already signed remain valid, and plants commissioned before entry into force keep their support conditions. In new contracts, check whether the lease is conditional on an EEG award, and agree the lease as an indexed fixed amount regardless of the marketing route. Until the law is passed, all of this remains a draft.
Lease Agreement: Term, Dismantling and Securities
The basic term of solar park lease agreements is usually 20 years and can be extended to 30 or 40 years via options. At the end of the contract, either repowering (new modules on the existing site) or dismantling follows. Make sure the following points are covered:
- indexation of the lease (linked to the consumer price index),
- a secured dismantling obligation (bond or reserve),
- clear rules on access and line rights,
- transparency about possible revenue sharing instead of or in addition to the fixed lease.
Which clauses matter in detail is explained in our guide to the photovoltaic lease agreement.
Fixed Lease or Revenue Sharing?
There are two basic lease models. The fixed lease pays you a guaranteed amount per hectare per year, plannable and independent of how much electricity the plant actually sells. Revenue sharing links part of your income to the solar park's electricity revenue; in high-yield years you earn more, in weak years less.
In practice, the fixed lease dominates because it leaves the risk with the operator. Some contracts combine both: a solid base lease plus a share that only kicks in above a certain electricity price. Which model makes sense for you depends on your risk appetite and the operator's creditworthiness. In both cases it is important that the lease is indexed and secured over the entire term, pure revenue sharing without a minimum lease can pay significantly less than expected in years of low wholesale prices.
Typical lease models in practice
Beyond the question of fixed lease or revenue sharing, two basic models have become established in practice. They differ above all in what the owner still has to do with the land after signing.
The most common model is the pure land lease: the owner provides the land, the developer plans, finances, builds and operates the solar park, and the lease is paid annually or quarterly at a fixed, indexed amount. This is particularly attractive for lessors in retirement or without a farm successor, because the income arrives without their own capital and without ongoing work. Many farmers use this model deliberately as a pension substitute: instead of selling land, they lease it for 20 to 40 years and secure a plannable income while the land stays in the family.
The second model combines lease income with continued use. The farmer maintains the vegetation under and between the modules, for example through sheep grazing or mowing, and receives a payment for this on top of the lease. Leasing and farming are therefore not mutually exclusive. Agrivoltaics goes a step further: crops are still grown or animals kept between elevated or vertical module rows. The lease is usually lower than for a classic ground-mounted system, but agricultural use is preserved. The mounting systems that make this possible are described in our guide on ground-mounted PV racking.
Whichever model you choose, the owner can normally keep farming the land until construction starts. For the period between signing and commissioning, which can take several years because of zoning, permitting and grid connection, an annual reservation fee should be agreed. It compensates for tying up the land and gives the developer an incentive to move quickly. Reputable developers offer it of their own accord; if it is missing from the draft, that is a negotiating point, not a deal-breaker.
Leasing in Four Steps
- Check the land: minimum size around 5 hectares (50,000 m²), unshaded, outside strict protected areas (e.g. Natura 2000). Do the first suitability check yourself in seconds above, free of charge and anonymously.
- Sign the brokerage agreement: if you want to obtain offers, you release your details and sign a brokerage agreement with ENLAPA, free of charge for you. Only on this basis do we present your land to vetted developers.
- Obtain offers: ENLAPA checks radiation, grid connection and eligibility and obtains offers from reputable investors for you.
- Sign the contract: you compare the offers, negotiate lease, indexation and dismantling, and secure long-term income.
In simple procedures it takes 12 to 18 months from first contact to commissioning of the solar park. If the land needs a zoning plan or the grid connection request sits in the grid operator's queue, it takes considerably longer, often several years. The process step by step is shown in our guide Building a solar park; the planning-law requirements are covered in Approval of ground-mounted PV.
How to Recognise a Reputable Offer
A good lease offer is realistic and transparent: a market-standard lease (€3,000–5,500/ha), a fixed indexation clause, a secured dismantling obligation and a financially strong operator experienced in electricity trading. Be cautious of inflated bait offers. Anyone promising €10,000 per hectare can rarely sustain that lease over 30 years. Have offers checked independently before you sign.
Lease, Usage Fee and Option Agreement: the Terms in the Contract
Anyone wanting to lease out solar land will find different names for the same payment in the draft contracts. Legally, a contract for a solar park is usually not an agricultural lease under Sections 585 et seq. BGB, because the land is not farmed but used for an installation. Many developers therefore speak of a usage or permission agreement (Nutzungs- or Gestattungsvertrag) and of a usage fee (Nutzungsentgelt) rather than a lease. For the amount and security of your income the label is irrelevant; what matters is the amount per hectare, the due date, indexation, term and the security provided by a limited personal easement in the land register.
The actual contract is often preceded by an option agreement. It gives the developer the right, for a limited period, to lease the land at the terms already fixed while zoning, permits and grid connection are clarified. Three points belong in every option: an annual option payment, a clear deadline with automatic expiry if the project does not go ahead, and the later lease as a fixed, indexed amount. An open-ended, unpaid option can in the worst case tie up the land for years without you seeing a single euro.
Property Tax, Municipal Participation and Sale: Who Pays What
Beyond the payment itself, leasing land for ground-mounted PV raises three side issues that should be settled in the contract. First, property tax: the owner remains liable, but passing it on to the operator is common, because solar use can change the tax classification of the land and increase the burden. The clause should also cover later increases. Second, municipal participation under Section 6 EEG: operators may pay host municipalities up to 0.2 cents per kilowatt-hour, and many municipalities expect this in return for the zoning plan. This payment comes out of the operator's electricity revenues and does not reduce your lease. Third, a sale of the land during the term: the contract continues with the buyer, the lease passes to them, and the registered easement is binding on every acquirer.
Anyone wanting to lease land for photovoltaic systems should settle these three points before signing, along with indexation and dismantling security. Whether your land qualifies as solar land at all is shown by the land check at the top of this page in a few seconds.
Land near the grid? Battery storage as a complement to the solar lease
If your land is close to a substation, it is worth a second look. Large battery storage systems pay €20,000 to 30,000 per hectare per year, a multiple of the solar lease, but usually need only 0.5 to 3 hectares. For them neither radiation nor soil quality matters, almost only the distance to the grid connection point and free connection capacity.
Since 23 December 2025, storage systems in the outer zone (Außenbereich) are privileged without a zoning plan in two cases: as a co-location storage system functionally linked to an existing renewable energy plant, for example next to a solar park (Section 35(1) No. 11 BauGB), and as a stand-alone storage system of at least 4 megawatts rated power located at most 200 metres from the property boundary of a substation (extra-high to high voltage or high to medium voltage), capped at 0.5 percent of the municipal area and at most 50,000 square metres per municipality (Section 35(1) No. 12 BauGB). For large arable plots the solar park usually remains the right use; a grid-near partial area can additionally go to a storage operator. Everything on lease, contract and permitting is in our guide Leasing land for battery storage systems.
Conclusion: what is your land worth?
Photovoltaic lease prices in 2026 are €3,000 to 5,000 per hectare per year, up to €5,500 at top sites. The ceiling is set by electricity revenue: at award values around 4.8 ct/kWh one hectare earns about €48,000 a year, and the lease is a share of 6 to 10 percent of that. Where your land lands within the range depends on grid proximity, radiation, EEG eligibility, plot shape and the number of bidders. Contractually, indexation, the reference area, the reservation fee and a secured dismantling obligation are what count.
Check your land now free of charge with the ENLAPA area check: within seconds you see from official geodata whether the land lies in the EEG area framework, which protected areas affect it and how far the nearest substation is. If you want to obtain offers, list your land and receive lease offers from vetted project developers.
Sources: Federal Network Agency (Bundesnetzagentur), press releases on the auctions for ground-mounted PV for the bid deadlines 1 March 2026 (12 May 2026) and 1 July 2026 (18 August 2026); Federal Statistical Office (Destatis), Agricultural Structure Survey 2023 (lease payments); Renewable Energy Sources Act Sections 4, 6, 37, 37c, 51, 101 and Federal Building Code Section 35(1) No. 11 and 12 (gesetze-im-internet.de); Netztransparenz.de, solar market values 2025/2026; German Solar Association (BSW-Solar), evaluation of the Market Master Data Register of 14 July 2026; Federal Government, cabinet decision on the EEG 2027 of 29 July 2026; Rödl & Partner on the EEG 2027 draft. Lease ranges: ENLAPA market observation. As of 7 October 2026. This article does not replace legal or tax advice.